Should you invest in a CFD? To know that, you must first understand the purpose and nature of it. A CFD is a short-term trading tool, not an investment you hold and compound. The published figures make the point: every regulated broker in the UK and EU must show how many retail clients lose money, and these numbers range from 68% to 89%.
This does not make CFDs useless. It makes them a specialist instrument with costs that punish long holding and leverage that punishes small mistakes. This guide explains how they work, what they cost, what the loss data show, and who they genuinely suit.
Key Takeaways
- A CFD gives you price exposure without ownership, so there are no shares, dividends or voting rights behind it.
- Leverage is the defining feature, and it works against you exactly as efficiently as it works for you.
- The published loss rates are the most reliable evidence available, because regulators require them.
- Holding costs make CFDs expensive over weeks or months, which rules them out as a buy-and-hold vehicle.
- Beginners are better served by owning assets outright before adding leverage.
What Is a CFD?
A contract for difference is an agreement between you and a broker to exchange the difference in an asset's price between the moment you open a trade and the moment you close it. Nothing changes hands but cash. You never own the underlying share, commodity or currency.
Say you buy a CFD on BP shares. If BP rises 8%, the broker pays you the cash equivalent of that gain on your position size. If BP falls 8%, you pay the broker. The movement settles in cash, and you never hold a single share.
CFDs can be written on almost anything: equities, indices, commodities, forex pairs, ETFs and cryptocurrency. This breadth is a large part of its appeal.
How Does CFD Leverage and Margin Work?
When you open a CFD position, you do not deposit the full value of the trade. You put up margin, a percentage of the position, and the broker covers the rest. This ratio is your leverage.
Suppose you want £10,000 of exposure to the UK 100 index. The margin requirement is 5%, so you deposit £500 and your leverage is 20:1.
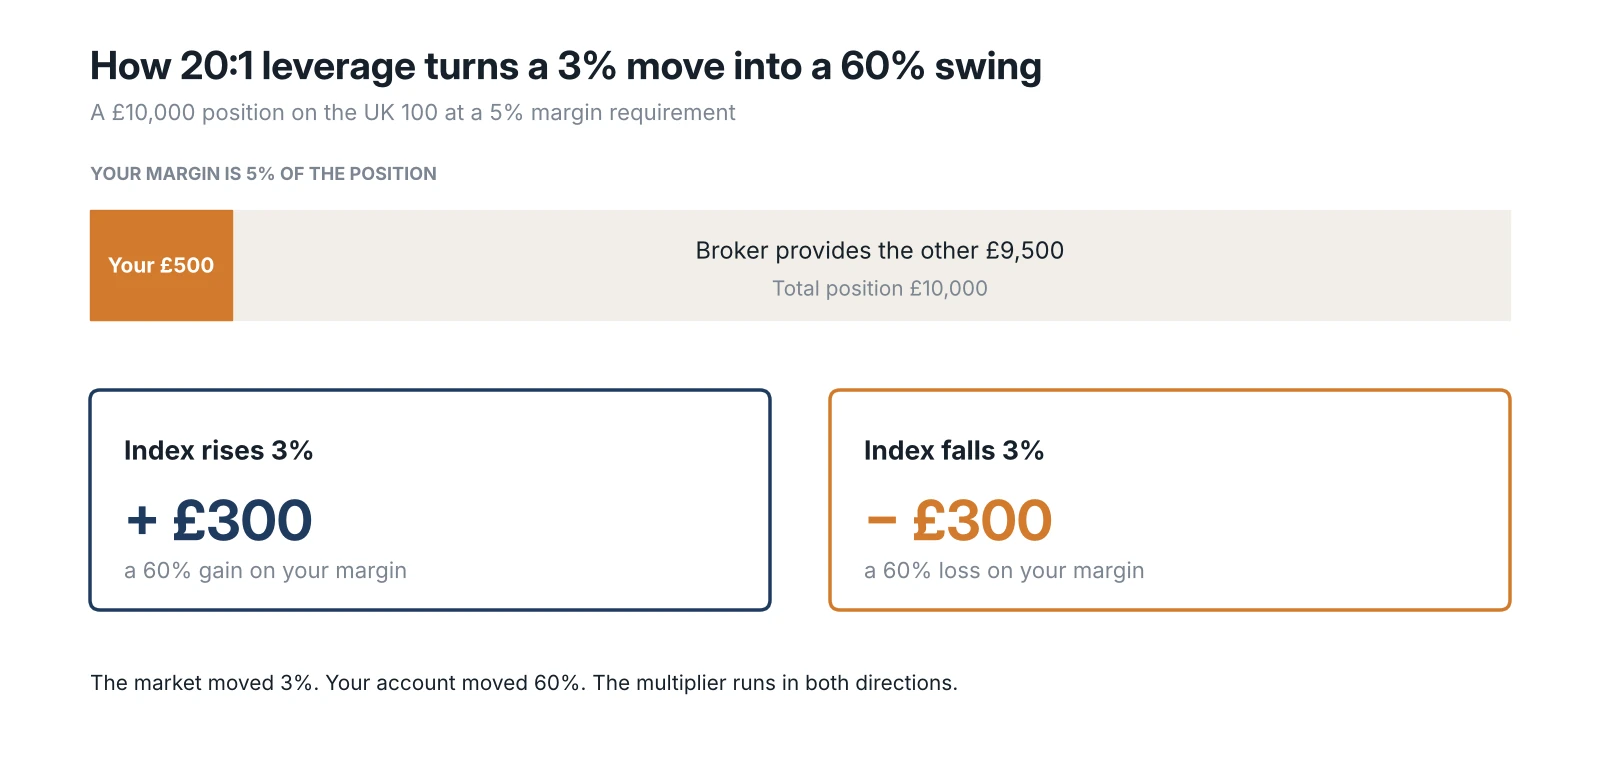
A 3% rise in the index earns you £300 on a £500 deposit, a 60% return on your margin. A 3% fall costs you £300, well over half of it. The market shifted 3%, but your account moved 60%. This multiplier is the whole proposition, and it runs in both directions.
There is also the margin call. If the market moves far enough against you, the broker asks for more funds or closes the position for you. Most regulated brokers apply negative balance protection, so a retail account cannot be pushed below zero into debt. Losing the full margin deposit is still the realistic downside, and it happens quickly at these ratios. Our margin calculator lets you size a position before you place it.
Leverage Caps by Asset Class
Retail leverage is capped by regulation. The European Securities and Markets Authority set the tiers in 2018, and the Financial Conduct Authority made matching rules permanent for UK retail clients in 2019.
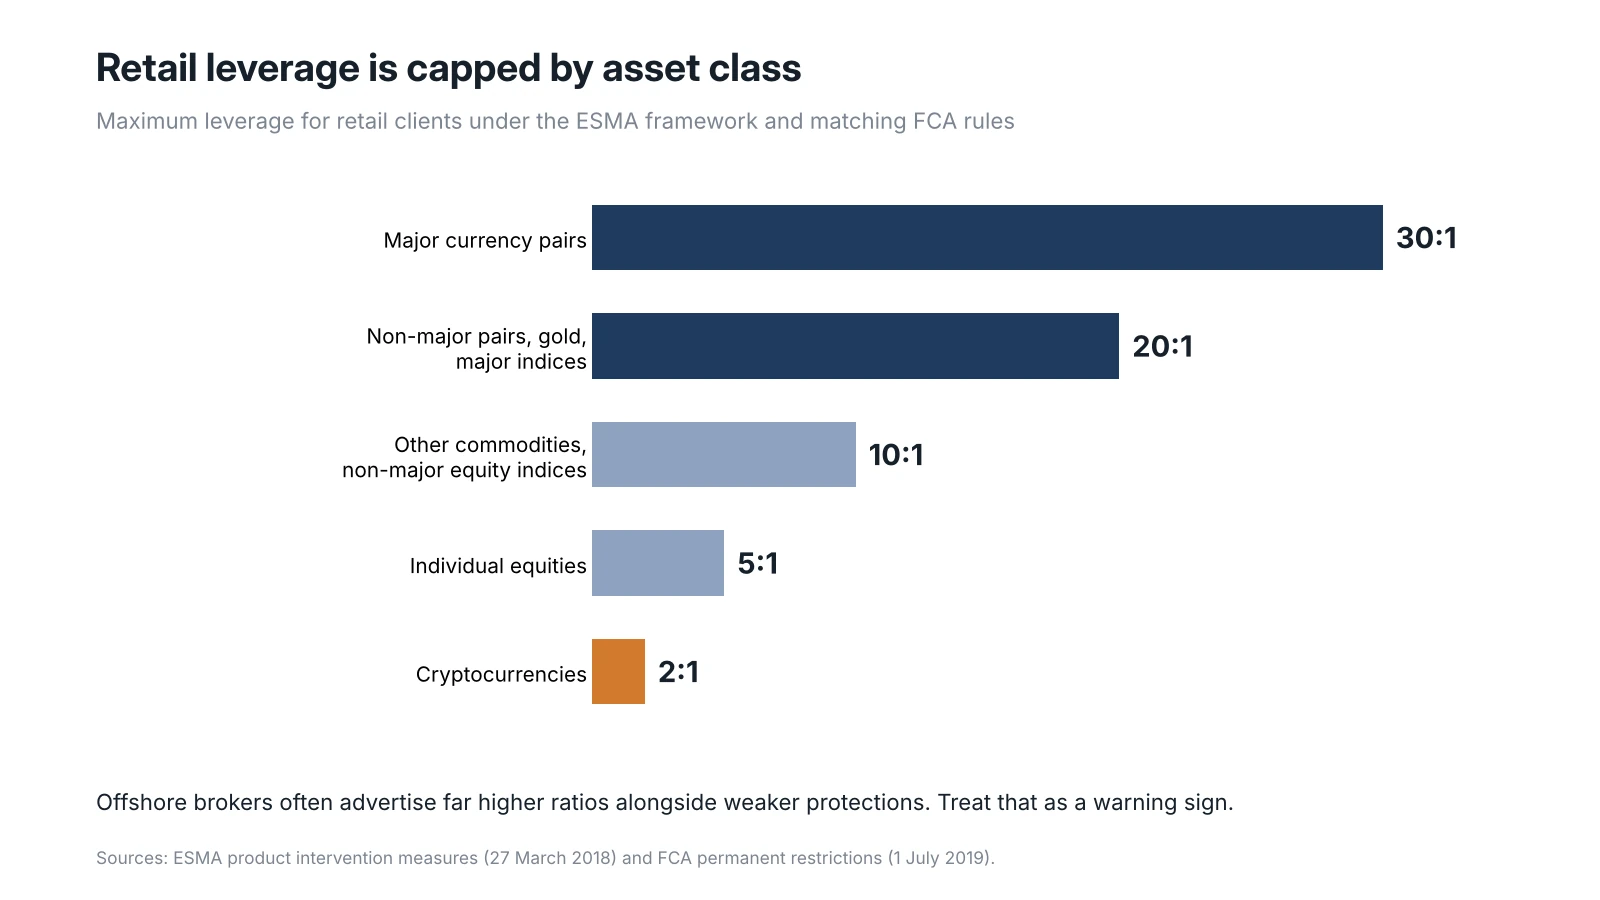
| Asset class | Maximum retail leverage |
|---|---|
| Major currency pairs | 30:1 |
| Non-major currency pairs, gold and major indices | 20:1 |
| Commodities other than gold, and non-major equity indices | 10:1 |
| Individual equities and other reference values | 5:1 |
| Cryptocurrencies | 2:1 |
Some offshore brokers advertise far higher ratios alongside weaker protections. See that as a warning sign rather than a selling point, and check the licence on the regulator's own register first. Our broker regulation guides explain what each licence covers.
What Are the Costs of CFD Trading?
Three costs come out of every CFD position, and leverage makes each one larger than it first appears.
- The spread: Every CFD has a buy and a sell price, and you pay the gap on entry. On EUR/USD that is typically 0.5 to 2 pips at a reputable broker. On thinner markets it widens, sometimes enough that the price has to move a long way before you break even.
- Overnight financing: Hold past the daily close and you pay a financing charge on the leveraged amount, usually the relevant benchmark rate plus around 2% to 3% a year. Over a few days, this is minor. But over a period of months, it compounds.
- Commission on equity CFDs: Many brokers add a per-trade commission on share CFDs, on top of the spread. Rates vary by broker and market.
The asymmetry is the point. On that £10,000 position, you funded with £500; the spread applies to the full £10,000, and so does the overnight charge. You pay costs on the whole position while risking only your margin.
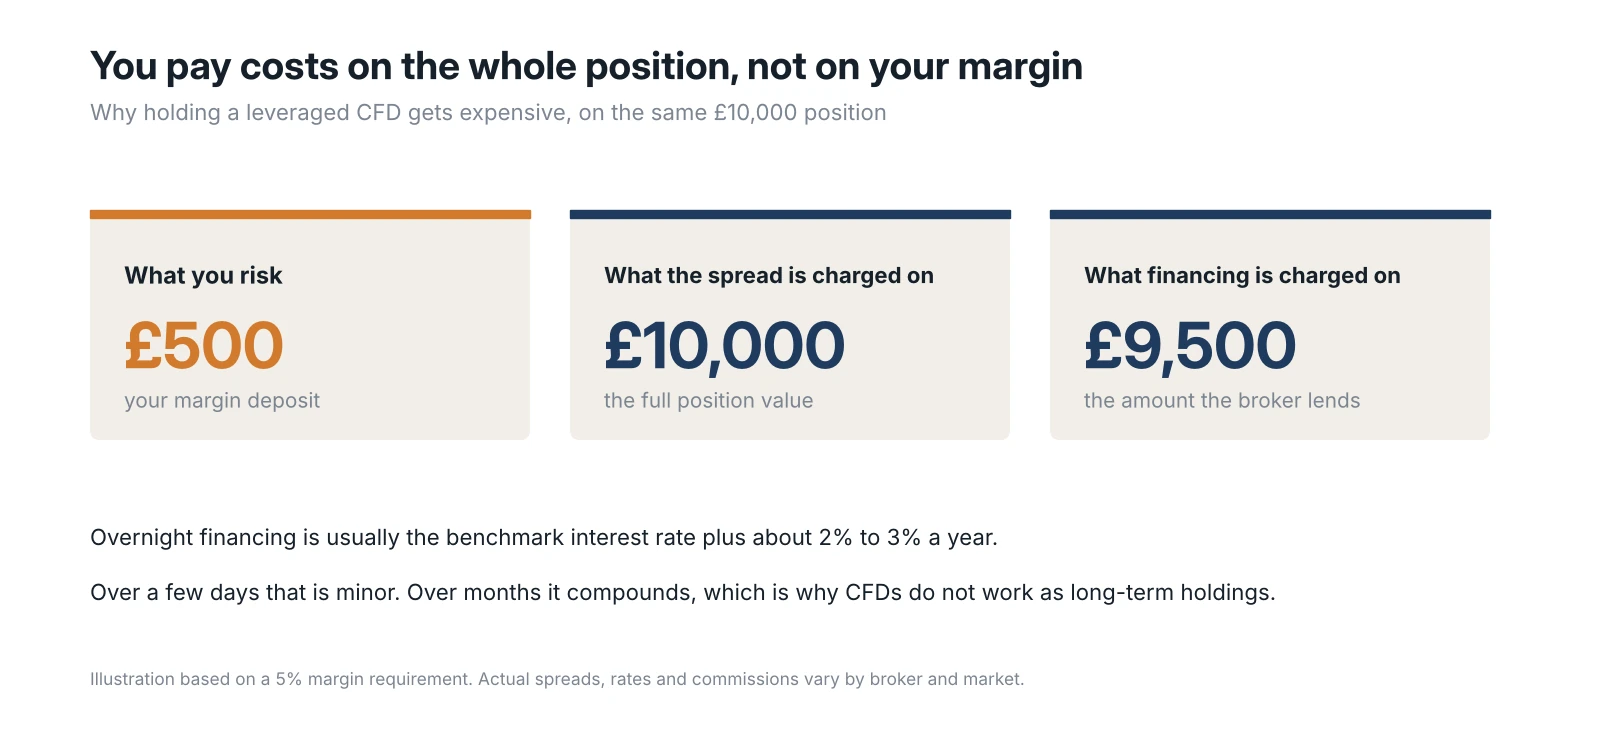
This is the mechanical reason CFDs do not work as long-term holdings, however appealing the ability to go long or short looks on paper.
What Do the Published Loss Numbers Say?
Regulated brokers in the UK and EU must display the share of their retail clients who lose money trading CFDs. The figures are reported, not estimated, and each broker updates its own.
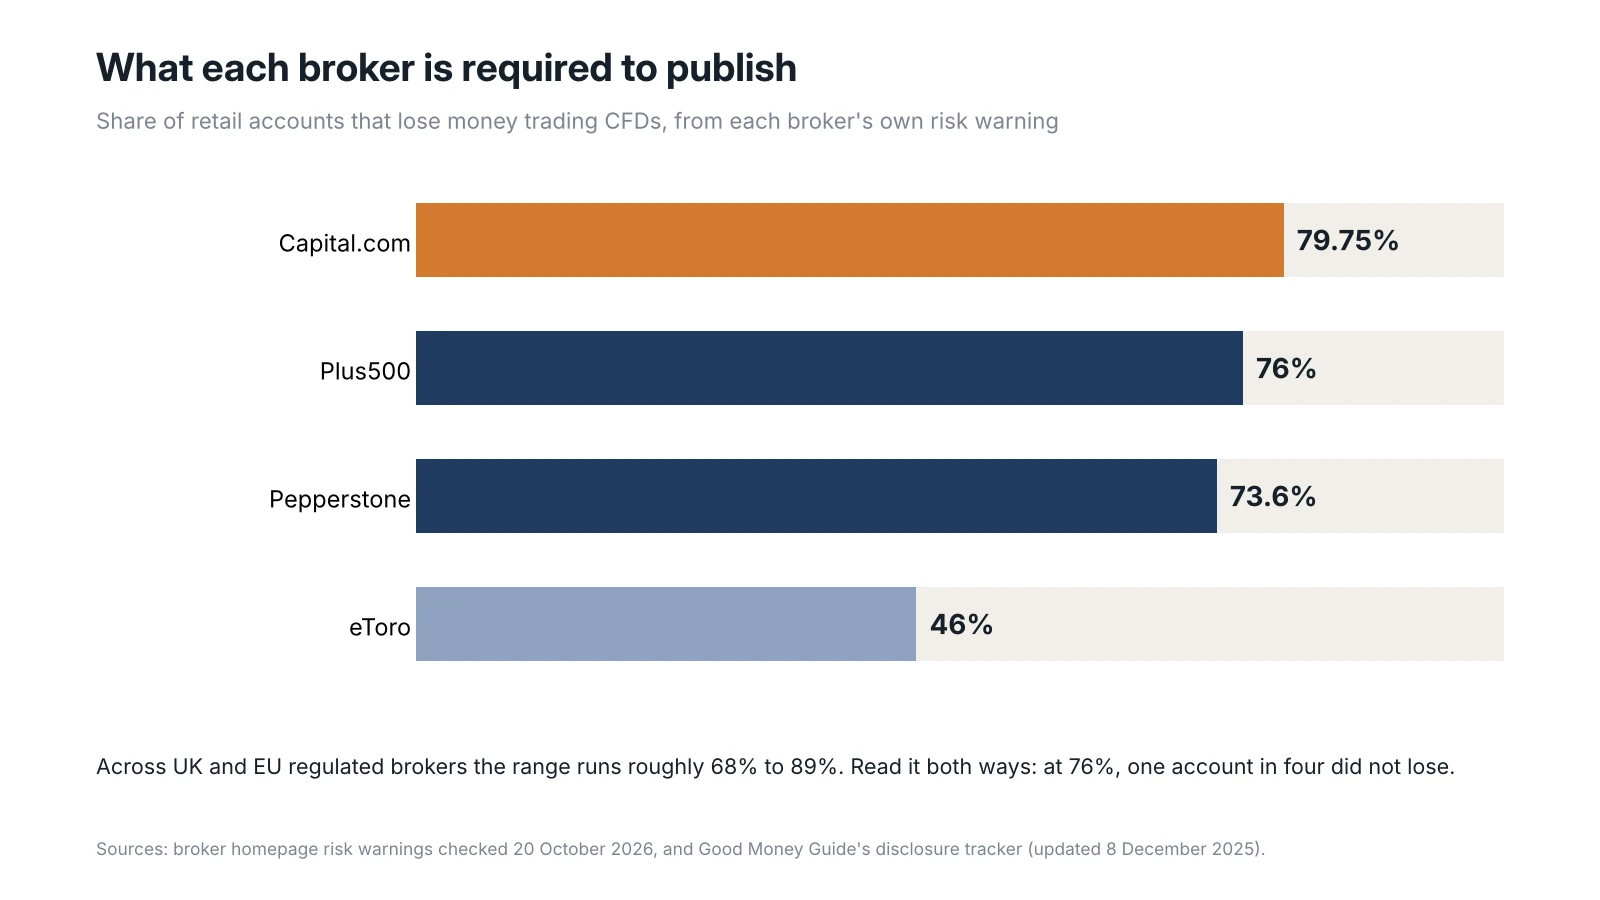
We checked four broker homepages on 20 October 2026. Capital.com displayed 79.75%, Plus500 76% and Pepperstone 73.6%. Good Money Guide's tracker of these disclosures puts eToro near 46%, the lowest among the major regulated names and usually attributed to a more passive client base, with Saxo, Spreadex and Interactive Brokers in a 60% to 70% band. Across UK and EU brokers the range runs roughly 68% to 89%.
Read the numbers the right way round. A figure of 76% means 24% of that broker's retail accounts did not lose money in the period measured. The disclosures count accounts over a rolling window rather than individual traders over a career, so they describe a market. They still describe a market where most participants lose.
Regulators consider the harm large enough to act on. When the FCA confirmed permanent CFD restrictions in July 2019, Christopher Woolard, then its Executive Director of Strategy and Competition, said: "Our intervention follows evidence of firms aggressively marketing CFDs to the general public" (FCA). The regulator estimated its measures would cut retail losses by £267.4 million to £450.7 million a year.
Why Do Most CFD Traders Lose Money?
Four things explain the loss rate, and none of them depends on picking the approach or direction.
- Leverage compresses the margin for error: At 20:1, a 5% adverse move takes the whole deposit. The position does not need to be wrong for long.
- Normal volatility triggers stop-outs: A trade can be right about direction and still be closed on a short-term spike before the move arrives.
- Costs run while you wait: Overnight financing erodes any position held longer than planned, which is most of them.
- You start behind: The spread means every trade opens at a small loss that the market has to cover first.
Experience changes the odds but does not reverse them. The traders who stay profitable tend to trade a tested system, size positions deliberately and accept small losses early, and most of them paid for that discipline with losses first. Our take on the life of a trader covers what that daily routine looks like in practice.
CFD vs Other Derivatives
Whether a CFD is the right tool depends on what else is available to you. These are the five main derivative types side by side.
| Derivative | Intermediary | Asset ownership | Customisable | Expiry | Leverage | Retail accessible |
|---|---|---|---|---|---|---|
| CFD | Broker | No | Limited | None, rolling | Yes, flexible | Yes |
| Forward | None, private OTC | No | Fully | Custom date | None formal | No, institutional |
| Futures | Exchange | No | No, standardised | Fixed | Yes, exchange-set | Limited |
| Options | Exchange or OTC | No, a right only | Some | Fixed | Premium paid | Moderate |
| Swaps | None, private OTC | No | Fully | Custom | None formal | No, institutional |
- Forwards: The oldest derivative. Two parties privately agree to exchange an asset at a future date and price, without an exchange, daily settlement or standard terms. This suits a company hedging a known currency receivable. There is no accessible retail market for them.
- Futures: The same idea as a forward, but exchange-traded, standardised and settled daily. They carry tighter regulation than CFDs and better liquidity on major markets, which is why institutions prefer them. Fixed contract sizes and exchange margin can mean a higher starting capital than the CFD equivalent.
- Options: These give you the right, but not the obligation, to buy or sell at a set price by expiry, in exchange for a premium. A buyer's maximum loss is the premium, which is a useful property. They are more complex to price and manage than CFDs.
- Swaps: Largely institutional. Two parties exchange cash flows, most often a fixed interest rate for a floating one, to manage exposure on existing debt. You will not meet them as a retail trader.
CFDs are the most accessible of the five for short-term retail trading. There is no expiry date to roll, leverage is flexible enough to size a position precisely, and the asset range is broad. You pay for that with ongoing costs without ownership benefits and outside the main regulated jurisdictions, weaker protection than exchange-traded instruments carry.
Who Should and Shouldn't Trade CFDs
A CFD makes sense if:
- You have a track record: You have traded on a demo or small live account before risking real capital. Our guide on whether demo accounts are accurate explains where the two differ.
- You want to hedge: Going short a correlated CFD protects an existing long portfolio against short-term downside without selling it.
- Your view is short term: You are trading a specific move, not buying something to hold.
- You understand the mechanics: Leverage, margin calls and overnight financing are clear to you before you open the position.
A CFD probably does not make sense if:
- You are starting out: You are still learning how price moves and how much a position can swing.
- You want to hold for the long run: Financing costs make that expensive, sometimes prohibitively.
- You want ownership: Dividends, voting rights and an actual stake need real shares.
- The money is not spare: You cannot afford to lose the capital you plan to trade.
For beginners, owning shares or index funds first is the cleaner route. You hold the asset, there is no margin to manage, and a poor decision costs you part of a holding instead of all the deposit. Our comparison of forex trading and stock trading sets out how the two differ before you add leverage to either.
Where Are CFDs Regulated and Banned?
CFDs are banned for retail clients in the United States, where CFTC and SEC rules keep them off the market. They are legal and regulated in the UK under the FCA, across the EU under national regulators applying the ESMA framework, and in Australia under ASIC, each with leverage caps and negative balance protection for retail accounts.
Regulation varies sharply beyond those markets, and plenty of offshore brokers accept clients from countries where they hold no local permission. Before you deposit anywhere, check the firm's licence on the regulator's own public register, such as the FCA register in the UK, the ASIC register in Australia or the CySEC register in Cyprus. You can also compare licensed options with our broker comparison tool.
The Verdict
So, should you invest in a CFD? If you are asking in order to build wealth over years, then you shouldn't. The costs are structured against holding, the leverage is structured against small mistakes, and the published loss rates show what usually follows.
If you are trading rather than investing, and you already have a method, a risk limit and the experience to follow both, a CFD is a reasonable tool for short-term exposure or for hedging a position you would rather not sell. See the maximum leverage on offer as a ceiling to stay well below, not a target, and start with money you can afford to lose entirely.
Frequently Asked Questions
Are CFDs a good investment for beginners?
Not really as a starting point. Between 68% and 89% of retail CFD accounts lose money, and beginners tend to sit at the higher end of that range because leverage punishes inexperience quickly. A better path is owning shares or index funds first, learning how far prices swing, then considering CFDs once you have a track record and a tested method.
What is the minimum amount needed to start CFD trading?
Some brokers accept deposits from around £50, but that is a marketing floor rather than a workable balance. You need enough margin to absorb normal volatility without being stopped out automatically. For a small CFD account, £500 to £1,000 is a more realistic starting point, depending on which markets you intend to trade and the leverage you use.
Are CFDs legal?
In most countries, though the United States is the notable exception, where CFTC and SEC rules keep them away from retail investors entirely. Elsewhere, legality usually depends on the broker holding permission in your country rather than on the product itself. An offshore firm can be legal where it is based and still lack any authorisation to serve you.
Do CFDs pay dividends?
Not directly. If you hold a long CFD on a dividend-paying share through the ex-dividend date, your account receives a cash adjustment equal to the dividend. On a short position, you pay that amount instead. It is a cash simulation rather than a real dividend, and in most countries it does not carry the tax treatment that a genuine dividend would.
What is the difference between a CFD and buying shares?
With a CFD, you never own the shares. You get leveraged price exposure, but no voting rights, no ownership and an ongoing financing charge for holding the position. Buying shares is simpler, cheaper over long periods and gives you a real stake. CFDs offer flexibility for short-term trading, including going short; direct ownership wins for long-term building.
Is CFD trading the same as investing?
No. Investing means buying an asset you expect to appreciate, holding it and compounding the return. CFD trading means speculating on short-term price moves using borrowed exposure. Leverage, financing costs and the absence of ownership all work against compounding. Treating CFD trading as a long-term investment strategy is one of the more expensive mistakes retail traders make.
